All Categories
Featured
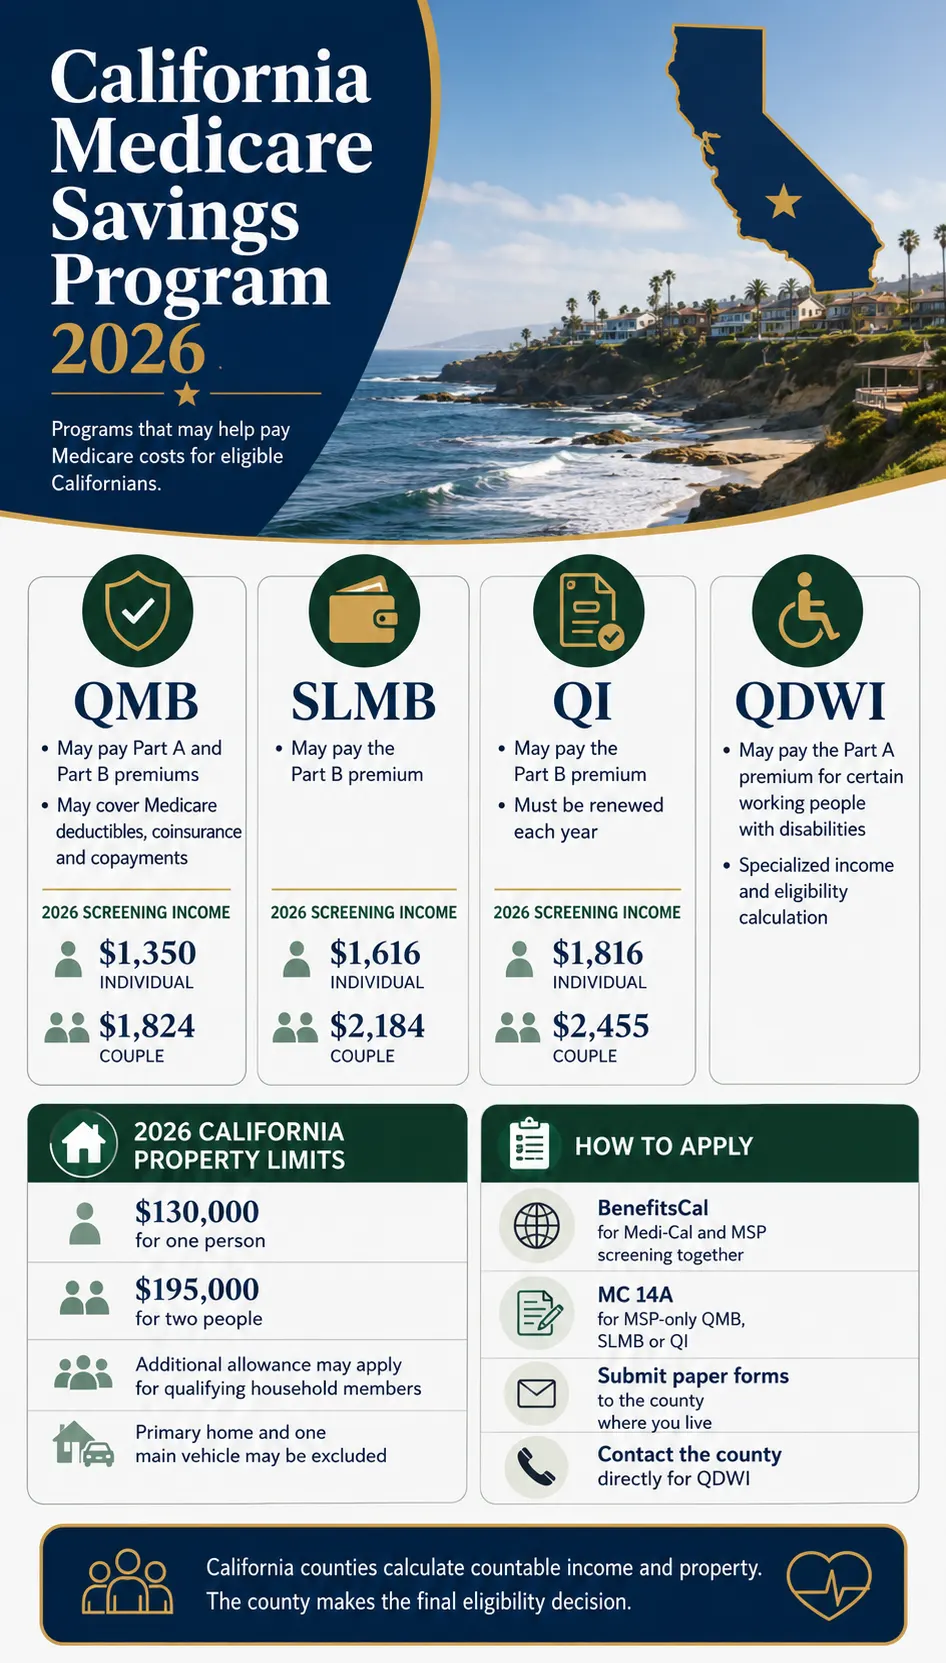

Steps to Optimize Health Insurance Premiums in CA
We then present choices side-by-side, discussing significant protection distinctions like replacement cost versus actual money worth, deductible structures, and recommendation choices., we evaluate both bundle policies and element coverage to find the most cost-efficient structure.
However our service continues long after the initial placement. We perform yearly reviews, provide certificates of insurance coverage for service agreements, response coverage concerns as they arise, and advocate during claims. When California regulations change or providers change their hungers, we proactively reach out to ensure your protection remains appropriate and competitively priced.
The replacement expense for a 2,500-square-foot home in Eagle Glen or Sierra del Oro might surpass $750,000 when accounting for California building regulations, permit fees, and present product and labor costs. Insuring to market price rather than replacement cost creates a hazardous space, particularly under California's rigorous coinsurance provisions. We assist Corona property owners determine accurate replacement costs utilizing local construction information, not out-of-date evaluations or county tax appraisals.
Comparing Independent Insurance Policies in Anaheim
While the Elsinore Fault does not create the exact same limelights as the San Andreas, it's capable of significant seismic occasions. Earthquake insurance through the California Earthquake Authority or private providers includes deductibles normally varying from 10% to 25% of home protection, indicating a $500,000 home may have a $50,000 to $125,000 earthquake deductible.

We help Corona house owners assess whether earthquake insurance makes monetary sense provided their equity position, emergency reserves, and risk tolerance. For Corona businesses, company interruption protection needs careful analysis of actual loss direct exposure and indemnity duration. A production operation may require 12 to 18 months of business disruption protection to account for devices replacement preparation and customer relationship rebuilding, while a retail operation may recuperate in 6 months.
We work through these scenarios with Corona company owner utilizing their actual financial information, not market averages that may not reflect their specific operations or supply chain dependences. Replacement expense computations for Corona homes utilizing existing Riverside County building and construction expenses, allow costs, and California building regulations requirements, not county assessor valuationsEarthquake deductible analysis comparing CEA and private market alternatives with assessment of out-of-pocket exposure versus annual premium investmentFlood zone determination for properties near the Santa Ana River, Temescal Wash, and Prado Basin with NFIP and private flood insurance coverage comparisonsBusiness disturbance duration examination for Corona organizations representing devices replacement lead times, supply chain healing, and consumer relationship rebuildingWorkers compensation classification accuracy making sure Corona companies aren't paying too much due to incorrect staff member category or market codesCommercial vehicle coverage for services running lorries on I-15, SR-91, and throughout Southern California with employed and non-owned car space analysisWildfire mitigation credit evaluation for Corona homes with defensible space, fireproof materials, or involvement in FireWise programsCyber liability limits assessment for Corona companies managing customer data, processing payments, or based on digital systems for operations.
A-MAX in Corona sits at 1520 West sixth Street, between the 91 and the 15 highways in the heart of Corona. If you live in Corona, near Norco, in Eastvale edges, or along the 6th Street-Magnolia corridor towards Riverside, strolling into our workplace is the fastest path. Walk-in service Monday through Saturday.

Latest Posts

Professional Guidance into Southern California Health Regulatory Shifts

Navigating Local Medicare Policies for 2026
Steps to Optimize Health Insurance Premiums in CA